The legal deadline: 2 years
Colorado's statute of limitations for property damage claims (C.R.S. 13-80-102) gives you two years. Homeowners hear that number and relax. That is a mistake.
Insurance Claims · Colorado Springs
Most roof replacements in Colorado Springs are insurance jobs, and the process has traps: two different deadlines, a percentage deductible most homeowners have never calculated, and out-of-state crews offering deals that are literally illegal here. This page is the whole process, in plain language.
We document first, meet your adjuster on the roof, and work under written SB 38-compliant contracts. No deductible games, ever.
How a claim works
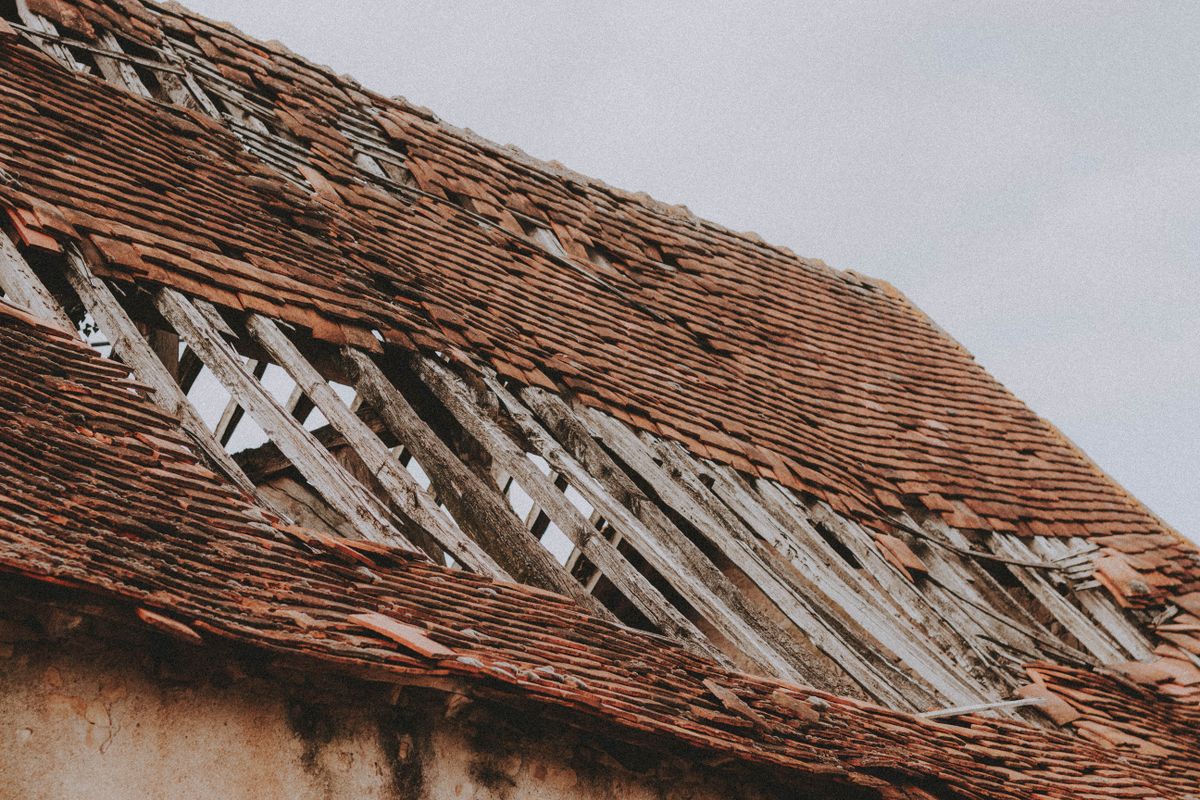
1. Document and inspect first. Before you file, we inspect the roof free and photograph functional storm damage slope by slope. If there is no storm damage, we tell you, and no claim ever touches your record. Start with the hail inspection page if a storm just came through.
2. File with the storm date. Your claim is tied to a specific storm event. We give you the date and documentation to file with.
3. Adjuster meeting. We meet your insurer's adjuster at the house, walk the roof together, and compare documentation so the scope of work matches the actual damage.
4. Build and final paperwork. Approved work is built under PPRBD permit. We submit the final invoice and certificate of completion so any withheld depreciation is released. From claim to completed roof typically takes 4 to 8 weeks.
Do not miss these
Colorado's statute of limitations for property damage claims (C.R.S. 13-80-102) gives you two years. Homeowners hear that number and relax. That is a mistake.
Most homeowners policies set their own notice deadline, commonly one year from the storm. Miss it and the claim can be denied as late-reported even though the legal deadline has not passed. The policy clock bites first, every time.
Damage from a storm last spring should be inspected and, if real, filed this season, not next. If you are not sure which storm damaged your roof, our inspection documentation and local storm records usually pin it down.
Colorado's SB 38 gives you a 72-hour right to rescind a roofing contract after a claim denial, and contracts must be in writing. A denial is also not always the end: documentation gaps can be addressed with a re-inspection request.
The deductible, honestly
Wind and hail deductibles in Colorado Springs are typically 1 to 5 percent of your home's insured dwelling value, not a flat $1,000. Two percent of a $500,000 home is $10,000 out of pocket. Know your number before you file, not after.
Colorado law (SB 38, C.R.S. 6-22-101) makes it illegal for a roofer to pay, waive, or rebate your deductible, or to advertise that they will. "We'll cover your deductible" is the single clearest storm-chaser tell in this state, and it can void your claim.
If documented damage costs less than your deductible, filing gains you nothing and adds a claim to your record. If it is a full replacement at $15,000 or more against a $5,000 deductible, the math flips. We run your numbers with you before you decide.
Replacing with Class 4 impact-resistant shingles triggers a premium discount most insurers must offer under C.R.S. 10-4-110.8, commonly 15 to 35 percent of the dwelling portion. One claim, years of lower premiums, and a roof built for the next storm.
Common questions
Colorado law (C.R.S. 10-4-110.8) bars insurers from raising premiums or dropping you over a single catastrophic-event claim. Weather claims are treated differently from negligence claims, and a storm that hit your whole neighborhood is exactly the catastrophic case.
Not on the porch. Check for a PPRBD license, which is the local license Colorado Springs requires since there is no state roofing license, a local address, and a written contract. Then get a second inspection. Ours is free.
The inspection, documentation, and adjuster meeting are free. We are paid for the roofing work itself when a claim is approved and built, at the scope the insurer sets. If nothing is approved, you owe us nothing.
On an approved claim, typically your deductible plus any upgrades you choose beyond the insurer's scope, like stepping up to Class 4. Our cost guide has the full per-square numbers.
Tell us what the roof is doing and we will schedule an inspection with full photo documentation. The inspection and the written quote are free.
Thanks, we got it. We will call you back shortly to schedule your inspection.